

Credit Genie

- 9.66K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on Credit Genie from Appgk
Credit Genie is the kind of finance app that makes a strong first impression because it tries to put several money-related tasks in one place. I found the appeal easy to understand: instead of moving between separate tools for credit information, everyday financial decisions, and account-related checks, you get a single starting point from Creditly Corp. It is free, aimed at Everyone, and presented as a “Credit Genie” rather than as a narrow budgeting spreadsheet or a traditional banking app.
That broad approach is useful, but it also creates an important question: does Credit Genie remain helpful after the initial curiosity wears off? My answer is cautiously positive. I think it earns a place on a phone for people who want a simple, recurring way to stay aware of their credit situation and make more informed money choices. However, it is not a replacement for a full bank application, a detailed budgeting system, or professional financial advice. Its long-term value depends on whether you use it as a regular checkpoint instead of expecting it to solve every part of your finances automatically.
What the first week feels like
During the first week, the strongest benefit is convenience. A finance app becomes useful when it reduces the effort required to answer ordinary questions: How am I doing financially? Has anything changed? Should I pay attention to my credit before applying for something? Credit Genie’s all-in-one positioning makes those questions feel less scattered. I can open one app, review the information available there, and decide whether I need to take action.
The free price also lowers the barrier to trying it. I would be more comfortable testing a tool like this without committing to a subscription, especially if I am still deciding whether credit monitoring belongs in my regular routine. The Everyone age rating makes it approachable for a broad audience, although younger users should still understand that financial decisions require care and that an app cannot replace an adult’s guidance when circumstances are complicated.
Best Parts of Credit Genie
Things to Keep in Mind About Credit Genie
The app was released on October 18, 2021, and its current version is 3.5.0. That history matters to me because a finance tool needs to feel maintained rather than abandoned after launch. I do not judge an app only by its first screen; I want to know whether it can become part of a repeatable habit. Credit Genie has had time to establish itself, and its presence at over 1 million installs, together with a 4.7 average from around 83 thousand ratings, suggests that many people find the overall experience worthwhile.
My practical advice for the first session is not to rush through everything simply because the app presents itself as a complete money companion. Start with one purpose. If your immediate concern is credit awareness, use that as your anchor. If you are checking your situation before a major purchase, write down what you need to understand before opening the app. This prevents the common problem of collecting information without turning it into a decision.
News and Features Related to Credit Genie

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Useful for a real everyday decision
Imagine I am considering replacing an old phone and may need financing. I would not open Credit Genie expecting a final approval or a guaranteed offer. Instead, I would use it earlier in the process, while I still have time to review my credit position and think about whether the purchase is sensible. That timing is one of the app’s more valuable use cases: it can encourage preparation before an application rather than panic after a lender has already made a decision.
The same workflow can help before renting a new home, comparing borrowing options, or planning a large household expense. I would check the app, note anything that deserves attention, and then verify important details through the relevant lender, bank, or official source. The app is most useful as a first checkpoint. Treating it as the only authority would be a mistake, particularly when a financial decision involves contracts, interest, deadlines, or information that may update at different times.
Don't want to read the full review?
One non-obvious advantage of this approach is psychological rather than technical: a low-friction check can make avoidance less comfortable. Many people ignore credit until they need it urgently. Having a dedicated app on the phone creates a visible reminder to look earlier. That does not improve a financial profile by itself, but it can improve the habit of noticing problems before they become expensive.
Why the value may continue after the novelty
A checkpoint is more realistic than constant monitoring
For month-to-month use, I would not open Credit Genie repeatedly throughout the day. Finance information is not entertainment, and frequent checking can easily turn into anxiety without producing a better decision. The recurring value comes from setting a sensible personal rhythm: a quick review when preparing for a major financial step, after an important account change, or as part of a monthly money routine.
Screenshots
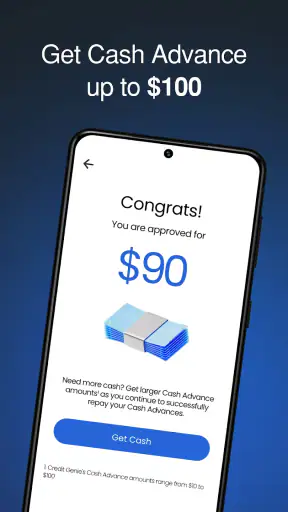
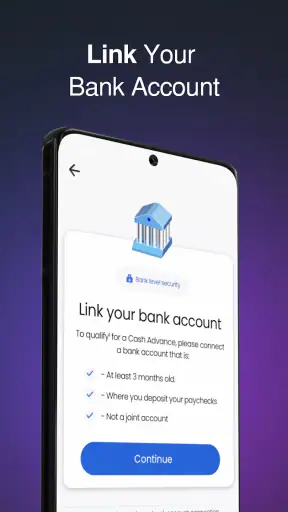
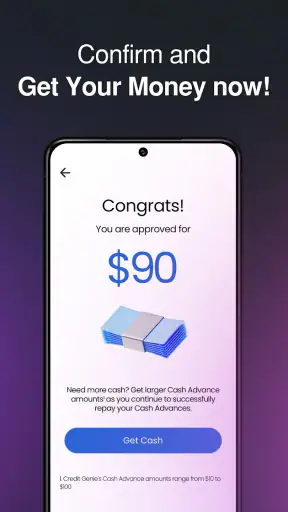
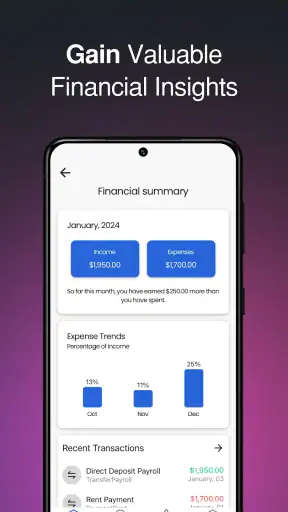
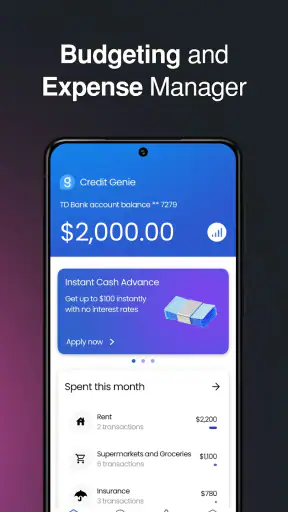
This is where the app compares favorably with doing nothing. A bank app may show balances and transactions very well, but it is not always designed to help me think about my broader credit position. A spreadsheet can track spending with more flexibility, but only if I build and maintain it. A credit-focused service may offer deeper specialization, while Credit Genie’s attraction is the attempt to keep relevant money information together in a more approachable experience.
The trade-off is depth. People who enjoy detailed categories, custom formulas, long-term forecasting, or household budgeting may outgrow an all-in-one credit app. I would choose a dedicated budgeting tool or a carefully maintained spreadsheet if my main goal were to understand every recurring expense. Credit Genie makes more sense when the primary need is awareness and direction rather than a complete accounting system.
Another useful habit is to record the action that follows each review. If I notice something that needs checking, I would write a short note such as “verify account detail,” “review application timing,” or “contact the provider.” This keeps the app from becoming a passive dashboard. The value is not in opening it and feeling informed; the value is in using what I see to decide what happens next.
Who benefits most over time
I see the best fit in people who are beginning to take credit more seriously, users preparing for a significant purchase, and anyone who wants a simpler first layer of financial awareness without paying to experiment. It can also suit someone who dislikes assembling information from several places and prefers a recognizable routine on a phone.
I would be less likely to recommend it as the main financial tool for someone with complicated finances, multiple businesses, extensive investments, or a strong need for precise cash-flow planning. Those users may need specialized services, professional support, or a system that exposes more detail than a general-purpose credit companion is designed to provide. The fact that an app tries to do many things is convenient, but convenience and completeness are not the same.
The maintenance burden is small, but not zero
Every finance app creates maintenance work, even when the interface feels simple. I need to keep my information accurate, read important notices rather than dismissing them, and understand what each displayed item means before acting on it. If the app connects to financial information, I also need to be comfortable reviewing access and security choices in the app and on my device. I would never install a finance app and then ignore basic account protection simply because it is convenient.
Credit Genie’s low ongoing burden is one of its strongest long-term arguments. It does not require me to build a complex budget from scratch just to get started. A short recurring review is easier to sustain than a detailed financial project that I abandon after a few weeks. Still, “easy to maintain” does not mean “set and forget.” Credit information can influence real decisions, so I would confirm important details with the original institution before disputing, applying, or committing to anything.
There is also a difference between app maintenance and financial maintenance. Updating the application to the current version, which is 3.5.0, helps keep the software current, but it does not replace reviewing my own accounts or correcting inaccurate information through the proper channel. The app can organize awareness; it cannot take responsibility for every underlying record or decision.
Where fatigue can appear
The first source of fatigue is breadth. When an app promises to handle many aspects of money, I may expect every area to be equally deep and equally useful. If I only care about one function, the rest can feel like visual noise. My workaround is to decide what I want from the app before opening it and ignore sections that do not support that goal.
The second source is alert fatigue. Financial notifications can be useful, but too many reminders can make me swipe them away without reading. I would keep only the notices that help me take a timely action and silence anything that adds worry without adding information. A good finance habit should make me more deliberate, not permanently nervous.
The third is false confidence. A clean summary can feel authoritative even when I have not checked the underlying context. I would treat Credit Genie as an interpretation and starting point, not as permission to borrow, spend, or assume that a lender will make a particular decision. This distinction is especially important when timing matters or when different institutions use different criteria.
There can also be fatigue from repetition. If every monthly visit shows nothing that changes my next step, the habit may lose its purpose. That is not necessarily a failure of the app; it may mean I am checking too often or asking it to provide entertainment from stable financial information. I would keep the routine only when it answers a real question, confirms that things remain on track, or prompts a useful action.
How it compares with familiar alternatives
Compared with a bank app, Credit Genie appears more focused on credit awareness and the broader decision around money rather than only showing the balance of one institution. A bank app remains the better place for transfers, account servicing, and transaction-level activity. I would use both if my financial routine required both kinds of information, because neither should be forced to replace the other.
Compared with a spreadsheet, Credit Genie is easier for someone who wants less setup. A spreadsheet wins when I need custom categories, formulas, shared household planning, or a historical record that I control directly. The app wins when I want a ready-made starting point and do not want to design a system before I can learn anything.
Compared with a specialized credit service, the choice depends on priorities. A specialist may be preferable for users who want the deepest possible focus on credit-related detail. Credit Genie’s advantage is its wider, friendlier role as a general money companion. I would choose it for simplicity and routine, not because an all-in-one label automatically guarantees the most detailed treatment of every financial subject.
That comparison also clarifies who should skip it. If I already have a trusted credit-monitoring system, a robust budget, and a financial routine that I follow consistently, adding another dashboard may create duplication rather than value. The app is not automatically useful just because it is free. Its place on my phone has to be earned by reducing friction or helping me notice something I would otherwise miss.
Questions I would answer before keeping it installed
Would I pay for it? The listed price is free, which makes the trial decision straightforward. I would still judge it by the time and attention it demands. A free app that creates confusion is not truly costless, while a simple tool that helps me take one good action each month can be worthwhile even without dramatic features.
Can it replace my bank? I would say no. I would keep using my bank’s own application for banking tasks and use Credit Genie as a separate layer for financial awareness. Keeping those roles distinct makes it easier to know where to verify information and where to complete a transaction.
Should I check it every day? I would not. A monthly or event-based routine is more sensible for most people. Daily checking makes more sense only when I have a specific reason and can interpret changes calmly. Otherwise, the habit can become noise.
Is it suitable before applying for credit? It can be useful as preparation, but I would not treat a screen in the app as a promise of approval, a final rate, or a substitute for reading the lender’s terms. I would use it to identify questions and then confirm the decisive details with the institution involved.
What if I find information that looks wrong? I would capture the relevant details, check the original account or provider, and follow the appropriate correction or dispute process. I would not assume that repeatedly refreshing the app will fix an underlying record. The app can help me notice an issue, but resolving it may require dealing with the organization that supplied the information.
My long-term verdict
After the first-week appeal fades, Credit Genie still has a reasonable case for staying installed because its value is tied to a practical habit rather than constant novelty. I like it most as a low-effort checkpoint: open it with a question, understand what deserves attention, and take the next step somewhere appropriate. That is a modest role, but it is a useful one.
The app is not for everyone. Detailed budgeters may prefer a spreadsheet, banking customers still need their bank app, and users with complex financial situations may need more specialized tools or advice. I also would not recommend passive trust. The broader the app’s promise feels, the more important it becomes to verify significant information before making a commitment.
Still, for someone who wants a free finance app that makes credit awareness easier to revisit, I think Credit Genie earns a trial and may earn lasting space. Creditly Corp has built an approachable product with strong user response, reflected in around 9.7 thousand written reviews alongside its 4.7 average. My recommendation is to keep the routine focused: use it before important decisions, review it at a sustainable pace, and measure it by the actions it helps you take. Its lasting value comes from turning financial awareness into a repeatable habit, not from pretending one app can manage every part of your money.
Credit Genie FAQ
What is Credit Genie and how does it work?
Credit Genie is a personal finance app designed to help users monitor and manage their credit-related information and everyday finances. Depending on your eligibility and location, it may provide tools such as credit monitoring, financial insights, cash advance options, or access to related services. After signing up, you typically connect or verify financial information so the app can present personalized features and recommendations.
Is Credit Genie a free app, or are there any fees?
Downloading Credit Genie may be free, but some features or financial services offered through the app can involve fees, subscriptions, expedited-transfer charges, or other costs. The exact pricing may depend on your location, eligibility, and the product you use. Before accepting an offer, carefully review the fee disclosure, repayment terms, automatic-payment conditions, and any applicable annual or recurring charges.
Does Credit Genie check my credit score or affect my credit report?
Credit Genie may request personal and financial information to verify your identity, assess eligibility, or provide credit-related services. Whether this involves a soft or hard credit inquiry depends on the specific feature and offer you apply for. A soft inquiry generally does not affect your score, while a hard inquiry may. Always read the authorization and disclosure screens before proceeding.
Is Credit Genie safe to use with my personal and banking information?
Because Credit Genie may handle sensitive information, users should review its privacy policy, security practices, permissions, and data-sharing disclosures before creating an account. Use only the official app-store listing, keep the application updated, and protect your account with a strong password and device security. Never share verification codes, passwords, or banking credentials with anyone claiming to represent the service.
Who can use Credit Genie, and what should I prepare before downloading it?
Availability and eligibility for Credit Genie can vary by country, state, age, income, banking relationship, and the particular service you want to use. You may need a valid government-issued ID, a supported bank account, a working phone number, and accurate personal details. Approval is not guaranteed, and using the app does not automatically mean you will receive a loan, advance, or credit offer.











